Winning Too Often? Here's How Sportsbooks Make You Pay for It
Photo: Jan Vašek, CC0, via Wikimedia Commons
Imagine you spend six months grinding out a positive return on NFL spreads. You're disciplined, you're doing your homework, and your bankroll is actually growing. Then one Tuesday morning, you try to bet $500 on a game and your max bet is suddenly $12. No email. No explanation. Just a number that makes the whole thing feel like a joke.
This isn't a hypothetical. It happens to bettors across the US every single week, at virtually every major sportsbook operating in the country. And if you're serious about betting smart, you need to understand exactly how it works — and what, if anything, you can do about it.
The Business Model Nobody Talks About
Here's the foundational tension: sportsbooks market themselves as skill-friendly entertainment platforms, but their actual business model depends heavily on recreational bettors who lose over time. When a customer consistently wins — especially on sharp, market-moving plays — they become a liability rather than a revenue source.
The response from most major US books isn't to improve their lines or accept the loss. It's to quietly manage the account into irrelevance. This can take several forms, and they rarely announce which one they're using.
Stake limits are the most common. Your max bet on a game drops from $1,000 to $50 with zero notice. You can still bet — they just make it economically pointless.
Market restrictions are subtler. You might find you can still bet sides and totals at normal limits, but player props — where you've been profitable — are suddenly locked or capped at a fraction of your usual amount.
Payout delays and account reviews sometimes follow a string of wins, with sportsbooks citing "verification" processes that seem to activate only when your balance is heading the wrong direction from their perspective.
Who's Doing This — And How Bad Is It?
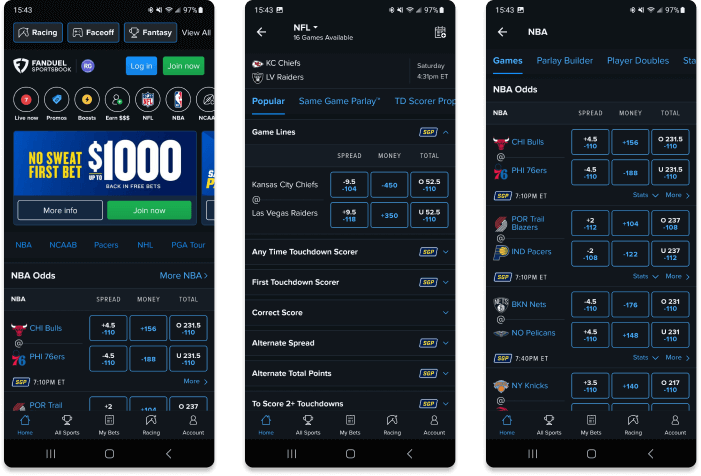
To be blunt: almost every major soft book in the US does this to some degree. DraftKings, FanDuel, BetMGM, Caesars — they're all running consumer-facing products optimized for recreational players. Their risk management teams are actively monitoring accounts for patterns that suggest sharp or professional-level betting.
The degree varies. Some books are more aggressive than others. BetMGM has developed a reputation among serious bettors for particularly aggressive limiting. FanDuel and DraftKings are somewhat more tolerant, though neither will let a consistently profitable account run indefinitely at full limits.
User reports on forums like Reddit's r/sportsbook and professional bettor communities tell a consistent story: the better you get, the smaller your betting universe becomes at mainstream books. One bettor documented being limited to $8 max bets at three separate books after a profitable NFL season — down from limits in the hundreds.
What Triggers the Scrutiny
Sportsbook risk teams aren't looking at individual wins. They're running pattern analysis. Here are the behaviors that tend to flag accounts:
Beating the opening line consistently. If you're regularly betting within the first hour of line release and your picks move in your favor, that's a sharp signal. Books notice.
Winning on correlated or exotic markets. Profitable player prop bettors get flagged faster than sides bettors in many cases, because the margins on props are thinner and the modeling is less sophisticated.
Arbitrage activity. If you're clearly middling or arbing between books, you'll get limited almost immediately. Books share data, and arb patterns are easy to spot.
High win rate on underdogs. Fading the public on underdogs consistently is a classic sharp behavior pattern. It shows up quickly in account analytics.
Depositing, winning, and withdrawing repeatedly. Books want recreational bettors who cycle money back through the platform. Quick withdrawals after winning streaks raise flags.
Strategies for Staying Under the Radar
This part requires some nuance, because there's no foolproof method — and some of these tactics are more ethical gray area than others. But here's what experienced bettors do to extend their shelf life at soft books:
Mix in some recreational-style bets. Parlays, same-game parlays, and other high-margin products signal to the algorithm that you're not purely a sharp. It's not ideal from a pure EV standpoint, but a small allocation to recreational play can buy you more runway at full limits on the bets that matter.
Spread your action across multiple books. Don't concentrate your volume at one sportsbook. Having active accounts at six to eight books — including some sharper-friendly offshore options — means no single book sees enough of your action to build a complete picture.
Avoid obvious arbitrage. Even if you're not technically arbing, betting both sides of a line at different books on the same day can trigger flags. Space it out.
Use sharp-friendly books for your serious plays. Pinnacle (available in some international markets), Circa Sports in Nevada, and a handful of others genuinely welcome sharp action. They make money on volume and efficient lines, not on limiting winners. If you're serious about long-term profitability, these should be your primary books.
The Bigger Picture
Account limiting is legal. Sportsbooks are private businesses, and their terms of service give them almost unlimited discretion to restrict or close accounts. There's no regulatory framework in the US that meaningfully protects winning bettors from this practice.
That's the uncomfortable reality. And it's one reason why the framing of sports betting as a skill game — which it genuinely can be — runs headfirst into a business model designed to extract money from people who aren't very good at it.
The best bettors in the country treat sportsbook accounts as a resource with a limited lifespan at any given platform. They extract value while they can, move on when they're limited, and build their strategy around books that can actually handle their action long-term.
If you're just starting to win consistently, enjoy it. But start thinking now about where you'll bet when the $8 limit email doesn't come — because it probably will.